BILL AP & AR Business Payments

Screenshots
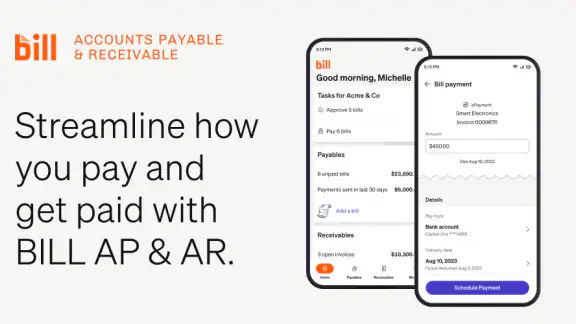
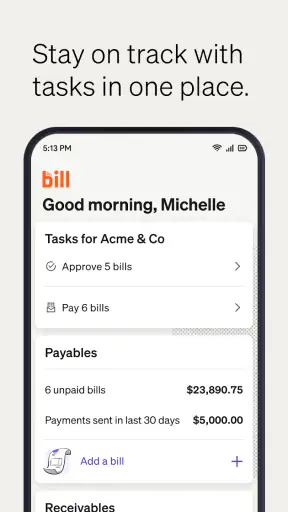
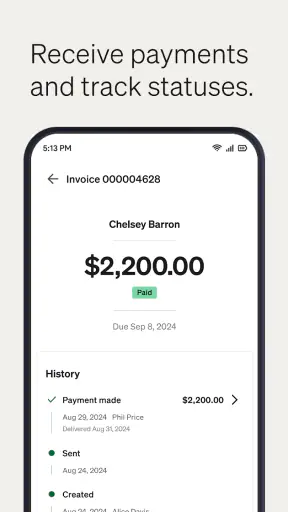
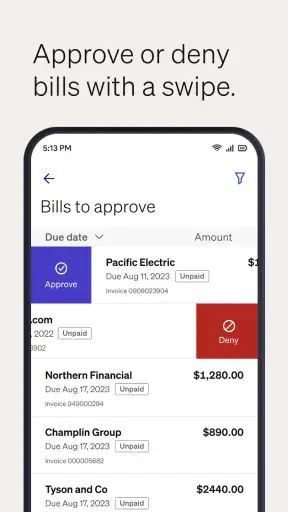
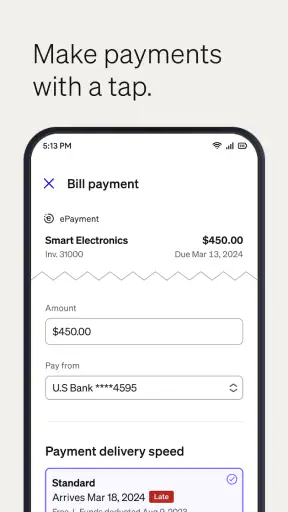
Details
- Rating
- 1.54K reviews
- Version
- 3.7.171
- Developer
- Bill.com Inc.
Analysis by Norviv
I approached BILL AP & AR as a practical business tool rather than something I would open for entertainment. Its job is straightforward: help businesses pay bills and get paid online. That sounds simple, but the real test is whether it can become part of a dependable monthly routine instead of being useful only during the first few days of curiosity. After spending time with it, I see a focused service from Bill.com Inc. that makes the most sense for small companies, freelancers, and teams that are tired of handling every payment conversation through scattered email threads and manual follow-ups.
The app is free, aimed at Everyone, and belongs to the Business category. It has built a respectable user base, with over 500 thousand installs, an average rating of 4.3, and around 7.5 thousand ratings. Those figures suggest that it is not an obscure experiment, although they do not remove the need to decide whether its workflow fits the way you already manage money. My opinion is positive, but conditional: BILL AP & AR is useful when you want a dedicated place for accounts payable and accounts receivable, while a very small operation with only a handful of monthly transactions may find a bank app or accounting package sufficient.
What the first week feels like
The first appeal is that the purpose is easy to understand. Instead of treating bills and incoming payments as separate chores spread across a banking app, inbox, spreadsheet, and accounting conversation, BILL AP & AR gives those activities a business-focused home. I found that clarity more valuable than flashy presentation. When an app deals with money, I would rather see a clear path for reviewing and acting on a payment than a collection of decorative screens.
The short description, “BILL AP & AR,” is almost blunt, but it accurately frames the experience. This is not a general personal-finance tracker, a shopping wallet, or a full replacement for every accounting task. It is built around the movement of business payments. That distinction matters because many disappointing app experiences begin with expecting a broad financial dashboard and discovering a narrower operational tool.
During the first week, the most useful habit is to treat the app as a checkpoint before money moves. I would not simply open it to glance at a balance and close it. I would use it when reviewing bills that need attention, checking whether an incoming payment has progressed, or preparing for a conversation with a colleague about what should be paid next. That makes the app feel more purposeful than a standard banking application, where business payment details can be mixed with unrelated account activity.
A realistic example is a small design studio that receives invoices from contractors while waiting for clients to settle their own invoices. The owner may begin the morning by reviewing outgoing obligations, then switch to receivables to see which customer payments need attention. The value is not that the studio suddenly avoids all financial administration. The value is that both sides of the payment cycle are considered in one business-oriented workflow, making it easier to keep today’s decisions connected to the cash coming in later.
I also like the possibility of using the mobile app between desk sessions. A business owner is not always sitting beside a laptop when a payment question appears. If a supplier asks whether an invoice is being handled, or a partner needs a quick status check, having a mobile route can prevent every small question from becoming a delayed evening task. I would still prefer to do careful review on a larger screen when many items are involved, but mobile access is useful for continuity.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
The first-week limitation is equally important: an app like this only becomes helpful when the business adopts it as part of its process. If invoices continue arriving in random email folders, approvals remain verbal, and payment decisions are recorded nowhere consistently, the app cannot create order by itself. The initial setup and change in routine may feel like work before the benefits appear. That is normal for a payment-management tool, but users should not mistake a clean first impression for an automatic solution.
Who gets immediate value
I think the strongest early users are businesses that have outgrown informal payment habits but do not want every financial task to depend on a desktop accounting workflow. A freelancer who sends occasional invoices may appreciate the organization, but may not need a dedicated accounts payable and receivable routine. A growing consultancy, agency, property-related business, or service company with recurring vendor and client activity is more likely to notice the difference quickly.
Teams can also benefit when payment work is shared. Even without turning the app into a complete company-management system, a central payment workflow can reduce the uncertainty that comes from asking, “Did anyone handle that invoice?” The important trade-off is that shared visibility only helps if everyone agrees on where the current status lives. If some people continue making decisions through private messages, the app becomes another place to check rather than the place to check.
For a sole proprietor, I would begin with one narrow use case instead of moving every financial record at once. For example, I might use it first for recurring supplier bills or for monitoring client payments. That approach makes it easier to judge whether the app saves time before committing to a broader change. It is a practical way to avoid the common mistake of installing a business app, importing too much activity, and abandoning it because the transition feels heavier than the original problem.
How it compares with familiar alternatives
The usual alternatives are a bank’s business app, an accounting platform, spreadsheets, and email. A bank app is often excellent for seeing transactions and moving money, but it may not provide the same payment-specific context that a business workflow needs. A spreadsheet offers flexibility and low commitment, yet it depends heavily on manual updates and can become unreliable when several people edit or interpret it differently.
An accounting platform may be the better choice when your main need is bookkeeping, reporting, tax preparation, or a broad view of business finances. BILL AP & AR is more appealing when the immediate pain is operational: keeping outgoing bills and incoming payments moving. I would not choose it simply because it is free. I would choose it if the payment process itself is the bottleneck and I want a focused companion to the rest of my financial tools.
Email remains deceptively convenient, especially for a very small business. The problem is that an inbox is organized around messages, not payment responsibility. A supplier’s reminder can be buried, a client’s response can be separated from the original invoice, and a decision can remain trapped in one person’s account. A dedicated payment app can reduce that fragmentation, but only if the team actually uses it as the working record.
Why the value can survive beyond the first month
The long-term value of BILL AP & AR is less about novelty and more about repetition. Bills arrive repeatedly, customers pay on different schedules, and someone must keep track of what deserves attention. A tool that makes those recurring moments easier has a chance to earn permanent space on a phone. I judge it less by whether the first session feels impressive and more by whether I would still open it during a busy month when the novelty has completely disappeared.
For me, the strongest recurring benefit is the separation between paying bills and getting paid. These are connected activities, but they create different pressures. Accounts payable asks what the business owes and when it should act. Accounts receivable asks what customers owe and whether expected money is arriving. Keeping both perspectives close encourages better daily judgment than looking only at the bank balance after transactions have already happened.
A useful monthly routine would be to review outgoing obligations at the beginning of a billing cycle, check incoming payments during the month, and use the app whenever a payment needs a decision rather than waiting for a crisis. That routine is more valuable than opening the app randomly. It also helps reveal whether the tool is earning its place: if it consistently helps me answer what needs attention next, it is doing meaningful work.
One non-obvious advantage of a recurring review is that it can expose process weaknesses. Suppose the same vendor bill repeatedly requires a last-minute search through email. The problem may not be the individual invoice; it may be that the business lacks a reliable intake habit. Using BILL AP & AR regularly can make that friction visible. I would then improve the handoff into the app, rather than blaming the app for a problem that begins before the payment record exists.
Another useful trade-off is the balance between speed and deliberate review. A mobile payment workflow can make it tempting to approve or respond quickly just to clear a notification. I think the app is most valuable when it supports a short but intentional check: confirm the bill or payment context, consider timing, and then act. The faster route is not always the safer route, particularly when a business has irregular cash flow or depends on a small number of large customers.
The app has been available since December 16, 2015, and its current version is 3.7.171. I mention that because longevity matters for a tool intended to become part of a business habit. A payment app is not something I want to replace every few months. Its established presence makes it easier to imagine using it as part of a continuing workflow, although the real test remains how comfortably it fits the company’s existing financial practices.
Maintenance is where the decision is made
No payment-management app is maintenance-free. The ongoing burden is not necessarily constant tapping; it is keeping the underlying information and responsibilities clear. Someone still needs to review bills, follow up on receivables, and decide what requires action. BILL AP & AR can organize that work, but it cannot replace judgment about cash flow, supplier relationships, customer communication, or accounting obligations.
I would assign a regular owner for the review process, even in a small team. Without ownership, a shared payment area can create a false sense of security: everyone assumes someone else is watching it. A short recurring check is better than opening the app only after a supplier complains or a customer asks why a payment has not been noticed. The app becomes more useful when it is connected to a named responsibility and a predictable business rhythm.
There is also a practical distinction between using the app for action and using it as the only financial record. I would not assume that a payment workflow replaces bookkeeping, document retention, or professional accounting advice. Businesses with complex reporting needs should keep the appropriate accounting process in place. BILL AP & AR makes the most sense as a focused layer for payment operations, not as permission to discard every other financial control.
My best maintenance tip is to start with a defined boundary. Choose the bills or receivables that cause the most repeated confusion, establish a consistent way to handle them, and observe the results for a few cycles. If the app reduces searching and follow-up, expand gradually. If it merely duplicates a system that already works, stop there. Free access lowers the financial risk of testing, but it does not eliminate the time cost of maintaining two overlapping workflows.
Where fatigue can appear
The first source of fatigue is duplication. If a business records the same payment in a spreadsheet, accounting software, email thread, and BILL AP & AR without a clear division between them, the app can increase administrative work rather than reduce it. Before adopting it seriously, I would decide which tool is the source of truth for each kind of information. The payment app should have a clear job, or it will become another inbox.
The second source is notification pressure. Payment work naturally creates reminders, questions, and decisions, and too much interruption can make users avoid the app. I prefer a workflow that encourages scheduled reviews while leaving room for urgent items. If every alert feels equally important, genuinely time-sensitive matters can lose their impact. The solution is not to ignore the app, but to create a habit that distinguishes routine checking from immediate action.
The third issue is organizational fit. A business with complicated approval rules, unusual payment arrangements, or many specialized accounting requirements may need a broader platform. BILL AP & AR could still be useful for a particular part of the process, but I would not force the entire company into it if the surrounding controls do not fit. A focused app is strongest when the problem is focused too.
Users should also ask whether mobile-first access matches their working style. I appreciate being able to stay connected to payment activity away from a desk, but detailed financial review can be easier on a larger display or within a full accounting environment. If you rarely make payment decisions from a phone, the mobile advantage may matter less. In that situation, compare the workflow itself rather than assuming a dedicated app is automatically better than the tools already on your computer.
Businesses that only send a few invoices and pay a few bills each month may reasonably skip it. A bank app plus a simple, disciplined record can be enough when the volume is low and one person handles everything. I would also look elsewhere if the main goal is personal budgeting, investment tracking, payroll, or tax preparation. Those needs sit outside the central reason I would install this app.
My long-term verdict
After the initial appeal fades, BILL AP & AR still has a credible reason to remain installed: it addresses a recurring business problem rather than a temporary curiosity. Its focus on accounts payable and accounts receivable gives it a clearer purpose than a general banking app, while its mobile form makes payment work easier to revisit during the day. I especially value the way it encourages me to think about money owed by the business and money expected by the business in the same operational context.
That recommendation comes with a condition. The app will not create a reliable process if the business does not decide who reviews it, what belongs there, and how it relates to accounting records. The lasting benefit comes from a routine: capture payment work consistently, review it at sensible intervals, and avoid duplicating the same information without a reason. In other words, the app rewards discipline rather than replacing it.
Its free price makes experimentation straightforward, and the Everyone content rating means it is broadly accessible as a business utility. I would still spend time testing it with real, low-risk workflow examples before making it central to a company’s payment operations. Start with a recurring bill group or a manageable set of client payments, then ask whether follow-ups are clearer and whether fewer tasks disappear into email.
My final judgment is that BILL AP & AR earns lasting space for small and growing businesses that need a dedicated payment routine but do not want to rely entirely on spreadsheets or a general-purpose bank app. It is less convincing for people seeking a complete accounting suite or for very small operations whose payment volume is too low to justify another system. If your recurring frustration is knowing what the business owes, what customers owe, and what deserves attention next, I would give this Business app a serious trial. If that question rarely causes trouble, your existing tools may remain the simpler choice.
Frequently Asked Questions
01What is BILL AP & AR Business Payments used for?
BILL AP & AR Business Payments is a business finance platform designed to help companies manage accounts payable and accounts receivable in one place. It can be used to send and receive invoices, schedule vendor payments, collect customer payments, organize transaction information, and improve visibility over outgoing and incoming cash flow. It is primarily intended for businesses rather than personal budgeting.
02Can small businesses use BILL AP & AR Business Payments?
Yes, the platform can be useful for small and growing businesses that want to reduce manual payment work and keep financial administration more organized. It may help owners, accountants, and finance teams handle bills, invoices, approvals, and payment tracking without relying entirely on spreadsheets. However, available features, pricing, user permissions, and transaction limits can vary depending on the selected plan and account setup.
03Is BILL AP & AR Business Payments safe for handling business payments?
BILL is built for business payment workflows and generally includes security measures such as account authentication, permission controls, payment verification, and transaction monitoring. Even so, users should protect login credentials, enable any available multifactor authentication, verify vendor and customer details carefully, and review payment approvals before submitting transactions. No online financial service is completely risk-free, so internal controls remain important.
04Does the app connect with accounting software and business tools?
BILL AP & AR Business Payments is designed to work alongside common accounting and business workflows, which can reduce duplicate data entry and make reconciliation easier. Depending on the current version, subscription, and region, integrations may be available for accounting platforms, banking services, expense processes, and other business tools. Before downloading or subscribing, check the official integration list to confirm compatibility with your software.
05Are there fees for using BILL AP & AR Business Payments?
The cost of using BILL AP & AR Business Payments depends on the service, plan, payment method, and account configuration. Some features may be included in a subscription, while payment processing, expedited transfers, international transactions, or other services may involve additional charges. Pricing can change, so businesses should review the official pricing page and applicable terms carefully before activating the account or sending payments.


